
Weekly Thesis
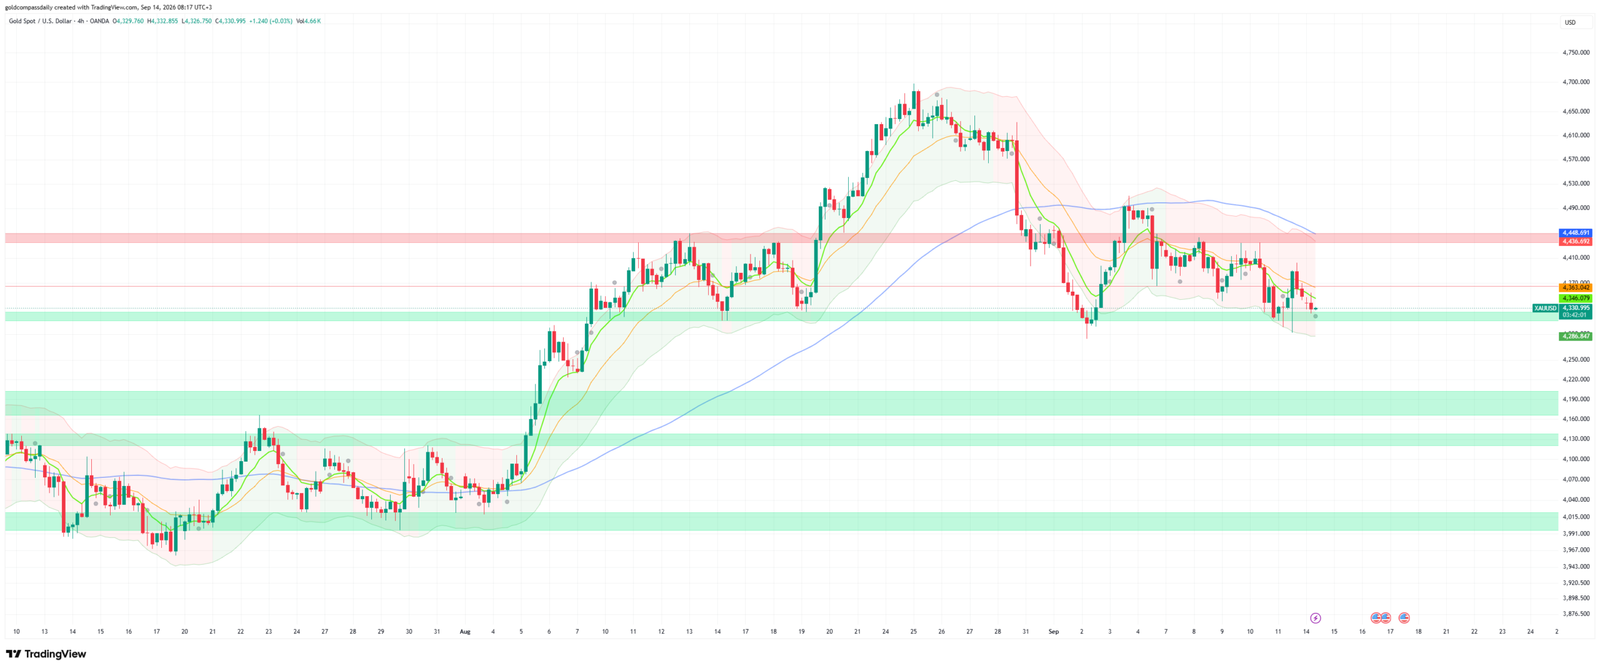
Gold enters the week of September 14–18, 2026 at $4,330 — defending a critical support zone that will either validate a bullish continuation toward $4,448 or open the door to deeper corrective losses toward $4,190, with the Federal Reserve’s September rate decision on Wednesday serving as the week’s defining binary trigger. The 4H chart shows price trading at the lower band of a multi-week consolidation range after last week’s pullback to $4,290, placing gold at maximum risk sensitivity to the FOMC outcome, the updated dot plot, and Fed Chair Warsh’s press conference tone. The overall macro structure remains bullish above the $4,200 region, but near-term momentum is bearish-to-neutral and the burden of proof this week lies with buyers at the $4,290–$4,330 support cluster.
Key Levels for the Week
- Weekly bias: Cautiously Bullish above $4,330 / Bearish on confirmed break below $4,290
- Immediate support: $4,290 → $4,265 (current cluster — chart support band)
- Secondary support: $4,190 → $4,160 (next major demand zone)
- Key resistance: $4,370 → $4,400 → $4,448 (weekly bull target zone)
- Weekly bull target: $4,448 — conditional on FOMC hold + dovish dot plot + buyers defending $4,330
- Weekly bear risk: $4,190 — conditional on FOMC hike or hawkish 25bps + dot plot projecting additional 2026 tightening
- The floor: $4,190 — break below invalidates the current bullish structure and opens $4,015–$4,040 zone on the 4H chart
The Week’s Defining Event: FOMC Rate Decision — Wednesday, September 16
The Federal Open Market Committee’s September decision — due Wednesday at 21:00 UTC — is not merely the biggest event of this week; it is the single most consequential macro catalyst gold faces in the third quarter of 2026. The Fed has held rates at 3.50%–3.75% at every meeting this year, but with market-implied odds for a 25-basis-point hike running between 30% and 58% depending on the data source and the week measured, the outcome is genuinely uncertain for the first time in months. Critically, this is a Summary of Economic Projections meeting, meaning the updated dot plot will be published simultaneously — and it is the dot plot, not merely the rate decision itself, that will move gold most decisively. If the FOMC holds rates but the dot plot signals one or two additional hikes before year-end alongside a revised upward inflation trajectory, gold is unlikely to stage a sustained rally even on a technical hold. Conversely, a hold paired with a dot plot that softens the hawkish language from June — or implies fewer hikes for 2027 — would constitute a meaningful dovish surprise and could be the catalyst gold needs to reclaim $4,400 and challenge $4,448 this week. Fed Chair Warsh’s press conference at 21:30 UTC will add a further interpretive layer: his track record of shortened, minimal FOMC statements means markets have learned to parse his spoken words for the guidance his written communications intentionally omit. The FOMC outcome will set gold’s directional range for the remainder of September; every other event this week is secondary.
Macro Context: What Gold Is Walking Into
From a technical standpoint, gold arrives at this week having pulled back sharply from its 2026 peak above $4,700 and now trades at the lower end of a range defined by the $4,290–$4,330 support band visible on the 4H chart. The moving average structure on the 4H is unambiguously bearish at current prices: the short-term exponential moving averages have crossed lower and are compressing toward the price, while the 20-period EMA sits in the $4,390–$4,400 zone — a level that has capped every recovery attempt since the late-August peak. The Bollinger Bands have narrowed, suggesting a directional expansion is imminent, and the FOMC is the most likely ignition point. The structure of higher highs and higher lows that defined the July–August rally remains intact on the weekly timeframe above $4,190, but on the 4H chart the price has been printing lower highs since the August peak, creating a bearish short-term pattern that must be resolved to the upside for a bull case to be credible this week.
The macro forces bearing on gold this week are pulling in opposite directions, which explains both the price compression and the elevated uncertainty around the FOMC outcome. On the bearish side: US Treasury yields have climbed in recent weeks as inflation expectations have been pushed higher by elevated oil prices stemming from renewed military action near the Strait of Hormuz. The June dot plot already showed nine of eighteen FOMC members favouring at least one additional hike in 2026, and that hawkish bias has not been walked back by public commentary in the intervening weeks. Sticky core inflation — with the US CPI reading from September 11 already absorbed by markets — has kept pressure on real yields, which remain gold’s primary rate-sensitive headwind. J.P. Morgan Wealth Management explicitly expects a 25bp hike on Wednesday. On the bullish side: geopolitical risk from the Middle East conflict continues to support gold’s safe-haven bid, central bank buying remains a structural floor with official sector demand running well above historical averages through Q2 2026, and Goldman Sachs holds to a hold call — implying that a significant portion of buy-side institutional money is positioned for a more benign outcome. The interplay between these forces means gold’s reaction to the FOMC will likely be amplified relative to normal meetings.
The Bank of England decision on Thursday and the Bank of Japan decision on Friday add further complexity to an already-dense week for gold. The BoE is expected to hold at 3.75%, with the MPC vote split anticipated at 3-0-6, maintaining the current cautious stance as UK inflation remains elevated — Wednesday’s UK CPI print (forecast 3.1% year-on-year) will arrive before the BoE votes, making the UK data sequence important. A hotter-than-expected UK CPI reading could reinforce global inflation-persistence narratives and strengthen the case for a more hawkish Fed dot plot, adding an additional bearish vector for gold into Wednesday’s FOMC. The Bank of Japan is expected to maintain its policy rate below 1.25% and below 1.00% respectively, with no meaningful shift in monetary policy anticipated — the BOJ decision and press conference on Friday are unlikely to move gold directly, but JPY-USD cross movements following any BoJ surprise could amplify gold’s post-FOMC direction. Retail Sales data from the US (Wednesday), UK Retail Sales (Friday), and US Industrial Production (Friday) round out the fundamental picture: strong US consumption data landing alongside a hawkish FOMC would be the worst-case combination for gold this week.
Daily Event Calendar: September 14–18, 2026
Monday, September 14
- 15:30 UTC — CAD CPI m/m (forecast: -0.1%): Canadian inflation prints typically move CAD and can influence broader commodity pricing — a miss on the downside softens North American inflation fears, marginally supportive for gold.
- 18:15 UTC — EUR ECB President Lagarde Speaks: Any shift in ECB tone toward further tightening could strengthen EUR, weaken USD, and provide short-term tailwind for gold — watch for commentary on eurozone inflation trajectory and the September rate path.
- Market tone: Positioning day ahead of a high-density week. Expect gold to consolidate in the $4,290–$4,350 range as traders take minimal directional risk ahead of Wednesday’s FOMC.
Tuesday, September 15
- 05:00–07:30 UTC — CNY Data Batch (Fixed Asset Investment, Industrial Production, Retail Sales, Unemployment): China’s activity data will signal whether the world’s largest gold consumer is seeing demand stabilisation — a strong Chinese Retail Sales beat supports gold’s physical demand narrative.
- 09:00 UTC — GBP Average Earnings Index 3m/y (forecast: 3.9%): UK wage growth above forecast keeps BoE hawks engaged and reinforces global wage-inflation persistence — a bullish dollar catalyst and negative for gold.
- 15:15 UTC — USD ADP Weekly Employment Change (prev: 12.0K): ADP labour data will be scrutinised as a pre-FOMC sentiment check on US labour market health — a strong number increases the probability of a rate hike and pressures gold.
- 15:30 UTC — USD Empire State Manufacturing Index (forecast: 14.1): Manufacturing surveys carry secondary weight this week, but a sharp positive or negative deviation from forecast could shift risk sentiment into the pre-FOMC window.
- EUR German ZEW Economic Sentiment (forecast: 42.7): Eurozone economic expectations data will indicate whether European growth momentum supports continued ECB tightening — relevant to USD/EUR cross and gold’s dollar-denominated price.
Wednesday, September 16 — FOMC Day
- 09:00 UTC — GBP CPI y/y (forecast: 3.1%): UK inflation print landing above forecast strengthens the global inflation-persistence narrative and increases market conviction for a hawkish FOMC — potentially the most important pre-FOMC data point of the week for gold.
- 15:30 UTC — USD Core Retail Sales m/m (forecast: 0.5%) / Retail Sales m/m (forecast: 0.8%): Strong US consumption data would validate the argument for an FOMC hike and weigh immediately on gold — this release lands approximately five and a half hours before the Fed decision and will likely move gold in the pre-FOMC window.
- 21:00 UTC — USD Federal Funds Rate Decision (forecast: 4.00% — implying a 25bp hike scenario; current rate: 3.75%): The week’s primary event. The rate decision, FOMC Economic Projections (dot plot), and FOMC Statement release simultaneously — this is gold’s directional trigger for the remainder of the week and likely the month.
- 21:30 UTC — USD FOMC Press Conference (Fed Chair Warsh): Press conference tone on the inflation outlook, future hike trajectory, and growth risks will amplify or moderate the initial reaction to the rate decision — Warsh’s stated preference for minimal communications makes his spoken words disproportionately market-moving.
Thursday, September 17
- 14:00 UTC — GBP Monetary Policy Summary / MPC Vote / Official Bank Rate (expected: hold at 3.75%, MPC vote 3-0-6): A surprise hawkish split or any dovish dissenter would move GBP significantly and could affect gold via USD cross effects — a hold-as-expected outcome allows the FOMC aftermath to continue driving gold.
- 15:30 UTC — USD Philadelphia Fed Manufacturing Index (forecast: 28.9): Philly Fed is a real-time gauge of mid-Atlantic manufacturing activity — a strong beat would reinforce the hawkish economic backdrop, keeping post-FOMC pressure on gold if a hike was delivered Wednesday.
- 15:30 UTC — USD Unemployment Claims (forecast: 209K): Initial jobless claims arriving a day after the FOMC decision will be filtered through the lens of the Fed’s updated labour market projections — a lower-than-expected number validates the FOMC’s economic assessment and reinforces any hawkish reaction.
- 15:30 UTC — USD Housing Starts / Building Permits (forecasts: 1.32M / 1.40M): Housing data is a lagging rate-sensitive indicator; below-forecast prints would suggest monetary tightening is gaining traction and complicate the case for further hikes — marginally supportive for gold.
Friday, September 18
- Tentative — JPY BOJ Policy Rate / Monetary Policy Statement / BOJ Press Conference (expected: hold below 1.00%): The BOJ decision is the day’s headline event — any surprise hawkish shift would strengthen JPY sharply, weaken USD, and could provide a secondary tailwind for gold into the week’s close.
- 09:00 UTC — GBP Retail Sales m/m (forecast: -0.2%): Weak UK consumer spending would confirm global demand softening — a secondary macro signal rather than a primary gold catalyst at this stage of the week.
- 13:30 UTC — EUR ECB President Lagarde Speaks: Post-Eurogroup Meetings commentary from Lagarde could provide updated ECB rate guidance — if she signals a pause or data-dependent stance, EUR weakness could marginally support a stronger USD and limit gold’s recovery.
- 16:15 UTC — USD Industrial Production m/m (forecast: 0.1%) / Capacity Utilization Rate (forecast: 76.4%): US production data will be the final major American economic release of the week — an inline or weak print would do little to override the FOMC decision already absorbed by markets.
- 16:30 UTC — USD FOMC Member Bowman Speaks / 18:45 UTC — USD FOMC Member Schmid Speaks: Post-decision FOMC commentary will be carefully parsed for any indication of internal disagreement or revised guidance on the pace of future tightening — hawkish dissenter voices would weigh on gold into the weekly close.
Weekly Bull and Bear Scenarios
Bull Case
Scenario trigger: FOMC holds rates at 3.75% on Wednesday, the updated dot plot removes or reduces the hawkish tilt from June’s projections, and Fed Chair Warsh’s press conference commentary emphasises data-dependence rather than a pre-committed tightening path. This outcome — which Goldman Sachs sees as the base case — would deliver a meaningful dovish surprise against current market pricing and trigger a sharp USD selloff. Gold would be expected to break above the $4,370 immediate resistance and the $4,400 supply zone, with the $4,330 support flipping to a new floor. Under this scenario, gold targets $4,448 by Friday, with a strong close above that level opening $4,510–$4,520 on the following week. Supporting conditions: UK CPI (Wednesday, 09:00 UTC) prints in-line or below forecast (reducing global inflation-persistence pressure), Chinese data Tuesday shows stabilising consumption (supporting physical demand narrative), and Bank of Japan delivers no hawkish surprise Friday (keeping risk sentiment stable). The BoE hold Thursday with an unchanged 3-0-6 vote would confirm that global central banks are entering a pause cycle — a broadly constructive backdrop for gold.
Bear Case
Scenario trigger: FOMC delivers a 25-basis-point hike to 4.00% or holds but releases a dot plot that signals two additional hikes before year-end with meaningfully higher inflation projections through 2027. Either outcome would validate the hawkish camp’s reading of the US economy, push real Treasury yields higher, and strengthen the dollar — the two most direct near-term headwinds for gold. Under this scenario, gold would fail to hold the $4,330 level and break through the $4,290 support zone confirmed as last week’s low. The next structural support sits at $4,190, which represents the weekly bear target and the zone Gold Compass Daily identifies as the week’s critical floor. Additional bearish acceleration: UK CPI Wednesday prints above 3.1% (compounding global inflation fears), US Retail Sales Wednesday beat significantly (validating a hawkish Fed), and US Unemployment Claims Thursday come in below 200K (showing labour market remains tight enough to justify additional tightening). A break below $4,190 on high volume would constitute a significant structural deterioration and shift Gold Compass Daily’s medium-term bias to bearish, opening a path toward the $4,015–$4,040 major support band visible on the 4H chart.
This Week’s Daily Analysis
- Monday, September 14 — Gold opens the week at $4,330, holding the critical $4,290–$4,330 support cluster as markets take a cautious stance ahead of Wednesday’s FOMC decision. ECB President Lagarde’s Monday afternoon address and Canadian CPI provide the day’s only tier-2 catalysts. Traders are expected to limit directional exposure with price likely ranging between $4,290 and $4,360 pending clarity from the Fed.
- Tuesday, September 15 — China activity data, UK employment figures, and the pre-FOMC ADP employment print make Tuesday a data-heavy session that could shift positioning ahead of Wednesday. Watch for gold’s reaction to ADP at 15:15 UTC — a strong labour number would increase hike probability and push gold toward the $4,290 support test.
- Wednesday, September 16 — FOMC Decision Day. UK CPI at 09:00 UTC and US Retail Sales at 15:30 UTC arrive as pre-Fed volatility inputs. The FOMC rate decision, dot plot, and FOMC Statement at 21:00 UTC define the week. Fed Chair Warsh’s press conference at 21:30 UTC will determine whether Wednesday’s close holds above $4,330 or breaks below $4,290.
- Thursday, September 17 — Post-FOMC follow-through session. Bank of England decision at 14:00 UTC, Philadelphia Fed Manufacturing Index, and Initial Jobless Claims at 15:30 UTC will confirm or complicate Wednesday’s directional move. A confirmed break above $4,400 Thursday would validate the bull case; a rejection and continuation lower would signal $4,190 is in view.
- Friday, September 18 — Bank of Japan policy decision and press conference (Tentative). FOMC members Bowman and Schmid speak, providing the final layer of post-decision guidance. US Industrial Production and Capacity Utilization round out the week’s data. Gold’s Friday close will set the technical tone for the following week — a close above $4,400 shifts the bias structurally higher; a close below $4,290 confirms bearish continuation into the following Monday.
Analysis based on the XAU/USD 4-hour chart as of September 14, 2026 at 08:17 UTC+3. This article is for informational and educational purposes only and does not constitute financial advice.