
Weekly Thesis
Gold enters the week of September 7–11, 2026 at $4,429.82 — compressed inside a tight consolidation coil following last week’s sideways digestion of the August 27 capitulation low, with price structure pointing cautiously bullish as two defining macro catalysts — Thursday’s ECB rate decision and Friday’s US CPI print — position the week as a genuine directional inflection point rather than further range extension.
Gold Compass Daily’s bias for the week is Cautiously Bullish. The technical base is building above the $4,350 structural support zone, short-term moving averages are beginning to re-curl upward, and the Bollinger Band compression visible on the 4-hour chart signals that a directional move is imminent. The question this week is not whether gold breaks from this coil — the data calendar guarantees it will — but which direction the macro evidence ultimately sanctions.
US Labor Day on Monday removes the world’s largest futures market from the session, compressing liquidity and raising the probability of false moves or thin-volume tests of nearby levels before the week’s true macro sequence begins Tuesday. Participants should calibrate position sizing accordingly for the Monday open.
Key Levels for the Week
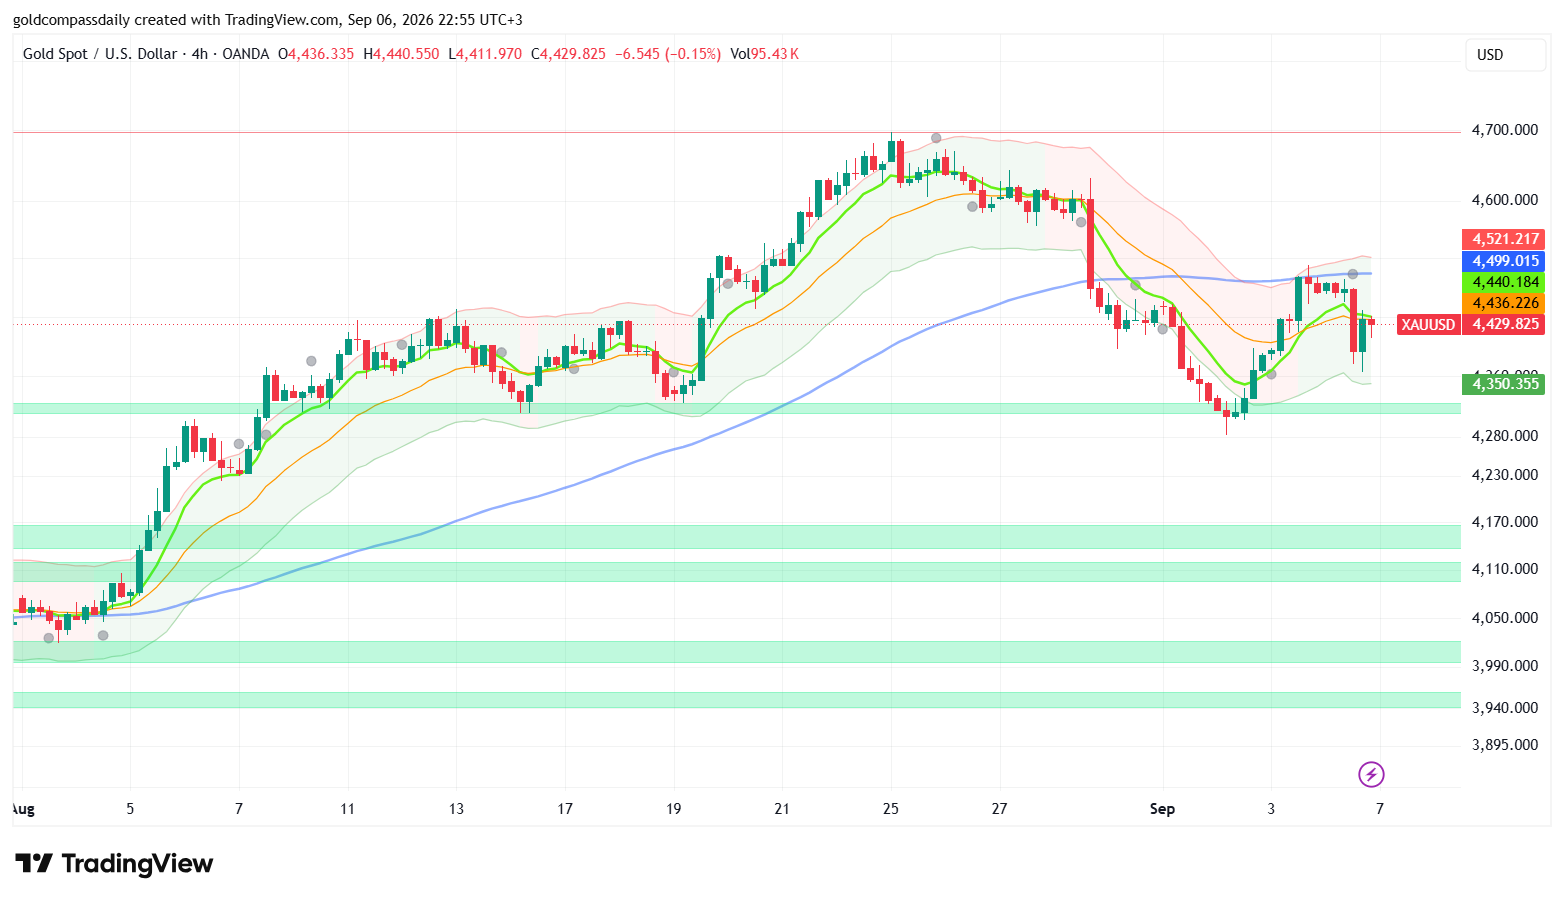
- Weekly bias: Cautiously Bullish above $4,350 — this is the structural floor that must hold for the recovery thesis to remain valid
- Key support: $4,350 (primary structural support / lower Bollinger Band / slow MA confluence) → $4,288 (secondary support / August capitulation demand zone)
- Key resistance: $4,440 (fast MA / immediate overhead) → $4,499 (medium-term MA resistance / 4H supply cluster) → $4,521 (upper resistance / prior breakdown level)
- Weekly bull target: $4,521–$4,560 — conditional on a soft US CPI print Friday and a dovish-leaning ECB press conference Thursday
- Weekly bear risk: $4,288 — conditional on a hot CPI surprise and/or a hawkish ECB holding rates higher-for-longer, triggering dollar strength
- The floor: $4,288 — a confirmed weekly close below this level invalidates the recovery structure and opens a retest of $4,170, calling into question the broader August uptrend
The Week’s Defining Event
Friday’s US Consumer Price Index release at 3:30pm UTC is the single event that will define gold’s directional trajectory for the week and, potentially, for the remainder of September. The data calendar contains multiple meaningful catalysts — the ECB decision, PPI prints, and bond auctions among them — but US CPI carries the decisive weight because it speaks directly to the Federal Reserve’s rate path, the trajectory of real yields, and the relative cost of holding non-yielding gold against dollar-denominated alternatives. The August CPI consensus sits at 3.4% year-on-year for the headline reading and 2.4% for core, with a monthly headline read of 0.4% representing the highest m/m expectation in the near-term calendar. A print that confirms or surprises to the downside on that monthly figure removes a key pillar of the “higher-for-longer” Fed narrative and gives gold the fundamental justification to break above the $4,499–$4,521 resistance cluster. Conversely, a hot CPI print — particularly one where core m/m exceeds 0.3% — would force a reassessment of rate cut timing, strengthen the dollar, and expose gold to a test of $4,288 and potentially lower. Every preceding data point this week, from Tuesday’s NFIB Small Business Index to Thursday’s PPI and Unemployment Claims, should be read as pre-positioning intelligence ahead of Friday’s verdict.
Macro Context
Where Gold Stands Technically After Last Week
The 4-hour XAU/USD chart entering this week tells a story of controlled digestion after a violent move. Gold staged a remarkable rally from the August 5 low near $4,050 all the way to a multi-month peak at approximately $4,670–$4,680 between August 19 and 21, establishing the uptrend’s high-water mark. The subsequent rejection was equally dramatic: a sharp liquidation on August 27 drove price from the $4,600s down through multiple support layers, printing a capitulation low near $4,280 before stabilizing in the $4,280–$4,350 horizontal demand zone — the same zone visible as the lowest green horizontal band on the chart. Last week’s price action was consolidatory and correct: gold traded sideways between approximately $4,350 and $4,510, closing the week’s sessions without conviction in either direction. This consolidation, while frustrating for directional traders, is technically constructive. It represents the market’s refusal to liquidate further into the $4,288 demand zone, and it has allowed the fast moving average (green, ~$4,440) and medium moving average (orange, ~$4,436) to begin decelerating and flattening, reducing the magnitude of the gap between price and its moving average anchors. The slow blue moving average, rising near $4,350, continues to provide dynamic support and has not been tested during this consolidation. The Bollinger Bands have narrowed markedly on the right side of the chart — a classic pre-breakout compression — confirming that last week’s sideways movement has coiled energy for a directional resolution this week.
The Macro Forces Supporting Gold This Week
The fundamental landscape entering the week of September 7 carries more supportive tailwinds for gold than headwinds, though none of them are unconditional. The overarching macro narrative remains one of peak-rate uncertainty: markets are actively debating whether major central banks, led by the Federal Reserve, have done enough to return inflation sustainably to target, or whether further policy tightening is still on the table. This uncertainty is structurally supportive for gold because it limits the magnitude of real-yield increases and reduces confidence in sustained dollar strength — both of which historically suppress gold demand. The BRICS Summit beginning Saturday, September 12, adds a geopolitical dimension that market participants are increasingly monitoring: the bloc’s ongoing discourse around dollar alternatives and reserve asset diversification represents a slow-burning structural bid for gold that does not disappear between data prints. Meanwhile, the global manufacturing weakness visible across this week’s data releases — German Industrial Production expected at a thin 0.1%, Italian Industrial Production recovering from a prior -1.0%, Japanese machine tool orders — collectively paint a picture of a world economy that cannot withstand significantly higher rates, implicitly capping central bank aggression and keeping gold’s relative attractiveness elevated. Central bank physical demand, which has been a defining feature of the 2025–2026 gold bull market, provides a floor of institutional buying interest that short-term technical tests cannot easily erode.
Central Bank Context: ECB Thursday Is Not Secondary
While US CPI Friday is the week’s headline event, Thursday’s European Central Bank rate decision deserves equal analytical attention from gold market participants, and not merely because of its direct euro implications. The ECB is expected to hold its Main Refinancing Rate at 2.65% — a decision that, if delivered with a dovish policy statement and a press conference from President Lagarde that signals the end of the tightening cycle, would weaken the dollar on a relative basis as European risk appetite improves. A weaker dollar environment is mechanically supportive for dollar-denominated gold. More importantly, any ECB language that acknowledges deteriorating Eurozone growth — evidenced by this week’s German Industrial Production, French Trade Balance, and Italian Industrial Production data — shifts the global rate conversation toward easing, which historically acts as an accelerant for precious metals positioning. Gold Compass Daily will monitor the ECB press conference at 3:45pm UTC on Thursday with particular attention to whether Lagarde signals concern about growth divergence within the bloc, as this would represent a meaningful shift in the communication tone that preceded September’s decision. If the ECB surprises with a cut to 2.40% — the consensus forecast embedded in some rate futures — the reaction in gold could be immediate and sharp, potentially triggering the move above $4,499 before Friday’s CPI arrives.
Daily Event Calendar: September 7–11, 2026
Monday, September 7 — US & Canada Bank Holiday (Labor Day)
- All Day — USD Bank Holiday (US Labor Day): US futures markets closed; gold trades on thin liquidity through Asian and European sessions only — elevated risk of false breakouts or sharp moves on low volume that do not represent true directional commitment; participants should reduce intraday sizing
- 09:00 UTC — EUR German Industrial Production m/m (Forecast: 0.1%, Prior: 0.2%): A consecutive deceleration in German industrial output confirms the Eurozone growth slowdown narrative, weakening the case for ECB hawkishness ahead of Thursday and providing marginal support for gold
- 11:30 UTC — EUR Sentix Investor Confidence (Forecast: 2.1, Prior: 0.9): An improvement in Eurozone investor sentiment, if confirmed, would reduce the urgency for ECB rate cuts on Thursday — a modest bearish nuance for gold’s immediate weekly setup
- 12:00 UTC — EUR Revised GDP q/q (Forecast: 0.4%, Prior: 0.4%): A confirmation of the Eurozone’s prior GDP reading at 0.4% quarterly growth would be neutral; any downward revision would accelerate the ECB dovishness narrative and support gold heading into Thursday
Tuesday, September 8
- Tentative — CNY Trade Balance (Forecast: 795B, Prior: 767B): A widening Chinese trade surplus, particularly if driven by rising exports, signals continued global demand activity and supports commodity-linked risk appetite — marginally constructive for gold as a risk-correlated safe asset
- Tentative — CNY USD-Denominated Trade Balance (Forecast: 120.1B, Prior: 112.5B): The dollar-denominated version of the Chinese surplus figure will attract cross-asset attention; a beat here reduces immediate safe-haven demand but confirms Chinese export engine resilience
- 13:00 UTC — USD NFIB Small Business Index (Forecast: 99.2, Prior: 99.8): A decline in small business optimism reinforces the narrative of softening US economic conditions; a reading below 99 would add weight to the “Fed has room to cut” camp and support gold ahead of Friday’s CPI
- 22:00 UTC — USD Consumer Credit m/m (Forecast: 13.2B, Prior: 14.2B): A continued deceleration in consumer borrowing signals that US household demand is softening — consistent with a disinflationary impulse and directionally supportive for gold’s Friday CPI setup
Wednesday, September 9
- 04:30 UTC — CNY CPI y/y (Forecast: 0.9%, Prior: 0.5%): A jump in Chinese consumer inflation, if confirmed, signals reflationary pressure in the world’s second-largest economy — this is a nuanced read for gold: mildly supportive as a global inflation signal, though Chinese CPI rarely moves XAU/USD directly
- 15:15 UTC — USD ADP Weekly Employment Change: The ADP employment figure provides the week’s first meaningful read on US labor market conditions; a weaker-than-expected print would strengthen the case for Fed easing and offer pre-positioning support for gold ahead of CPI Friday
- 20:01 UTC — USD 10-Year Bond Auction (Prior: 4.68% yield): A strong 10-year auction — indicated by a high bid-to-cover ratio and a yield that clears below 4.68% — would drive real yield expectations lower and provide direct support for gold; a weak auction (tail) that forces yields higher would pressure gold in the $4,440–$4,499 resistance zone
- 20:00 UTC — EUR German Bundesbank President Nagel Speaks: Any commentary from Nagel that pre-signals Thursday’s ECB decision, particularly language around growth concerns or inflation undershooting, would move gold markets in thin Wednesday evening conditions
Thursday, September 10 — The ECB Decision
- 15:15 UTC — EUR ECB Main Refinancing Rate Decision (Forecast: 2.65%, Prior: 2.40%): The ECB rate announcement is the day’s pivotal event — a hold at 2.65% with dovish forward guidance is the base case and already partially priced; any surprise cut to 2.40% would be a catalyst for a sharp gold rally through $4,499 resistance
- 15:45 UTC — EUR ECB Monetary Policy Statement & Press Conference: Lagarde’s tone on Eurozone growth, inflation persistence, and the rate path beyond September matters as much as the rate decision itself — watch for language acknowledging manufacturing weakness and any softening of the “data-dependent” phrasing that has characterized recent guidance
- 15:30 UTC — USD Core PPI m/m (Forecast: 0.3%, Prior: 0.2%) & PPI m/m (Forecast: 0.4%, Prior: 0.0%): The producer price inflation data arriving simultaneously with the ECB decision creates a volatile cross-current — a hot PPI (particularly headline at 0.4%) would lean against any gold rally the ECB triggers; a soft PPI would amplify a dovish ECB response and pre-validate Friday’s CPI soft-landing narrative
- 15:30 UTC — USD Unemployment Claims (Forecast: 205K, Prior: 206K): Claims holding steady near 205–206K signals a labor market that remains resilient without overheating — the “goldilocks” read that reduces both recession risk (which would hurt gold sentiment) and inflationary pressure (which would hurt the Fed easing case)
- 21:00 UTC — USD 30-Year Bond Auction (Prior: 5.22% yield): Long-end bond auctions affect the real yield curve that gold prices trade against; a weak 30-year auction forcing the long end above 5.22% would create a meaningful headwind for gold into Friday
Friday, September 11 — The Week’s Verdict
- 15:30 UTC — USD Core CPI m/m (Forecast: 0.2%, Prior: 0.2%) & Core CPI y/y (Forecast: 2.4%, Prior: 2.5%): The core CPI year-on-year reading declining from 2.5% to 2.4% — if confirmed — represents the clearest signal yet that the Fed’s final mile of disinflation is in progress; this is the single most bullish macro outcome possible for gold this week
- 15:30 UTC — USD CPI m/m (Forecast: 0.4%, Prior: 0.1%) & CPI y/y (Forecast: 3.4%, Prior: 3.4%): The 0.4% monthly headline expectation represents the largest m/m CPI forecast in the near-term calendar — if this prints in line or above, it will test whether the core softness narrative holds; a monthly headline below 0.3% would trigger a significant gold rally
- 17:00 UTC — USD Prelim UoM Consumer Sentiment (Forecast: 51.0, Prior: 51.7) & Inflation Expectations (Prior: 4.0%): Consumer sentiment at cycle lows near 51 confirms demand destruction that reinforces the disinflationary case; the inflation expectations component is watched closely by the Fed — any decline from 4.0% would amplify the gold-positive CPI reaction
- 09:00 UTC — GBP GDP m/m (Forecast: 0.0%, Prior: 0.3%): A flat UK growth reading signals economic stagnation in a major G7 economy — while not directly driving XAU/USD, a weak UK GDP print reinforces the global growth slowdown narrative that keeps central banks on an easing trajectory and supports gold’s safe-haven premium
- Tentative — USD Fed Monetary Policy Report: The Federal Reserve’s formal monetary policy report, if released Friday, provides the institutional forward guidance narrative that markets will anchor to heading into the September FOMC decision — any language in the report that strengthens the case for an imminent rate cut would provide a sustained tailwind for gold beyond the intraday CPI reaction
Weekly Bull and Bear Scenarios
Bull Case — Target: $4,521–$4,560
The bull scenario activates when at least three of the following conditions are met in sequence. First, Monday’s low-liquidity session holds above $4,350 without testing the structural floor, confirming the consolidation base is holding rather than cracking. Second, Tuesday’s NFIB and Consumer Credit data prints softer than consensus, reinforcing the softening US economy narrative. Third, Wednesday’s 10-year bond auction clears at or below the prior 4.68% yield, keeping real yields anchored. Fourth — and most critically — Thursday’s ECB decision is accompanied by a dovish press conference that signals the end of the tightening cycle in Europe, while simultaneously PPI data prints at or below the 0.4% headline forecast. This combination weakens the dollar on a cross-rate basis and triggers gold’s first meaningful breakout above $4,440 and into the $4,499 resistance cluster. Fifth, Friday’s CPI delivers: Core CPI m/m at 0.2% as forecast (or below), Core CPI y/y declining to 2.4% from 2.5%, and headline monthly at or below 0.3%. This combination — a soft CPI confirming disinflation — would validate the Fed’s ability to pivot toward rate cuts, collapse real yield expectations, and drive gold through $4,499 toward the week’s bull target of $4,521–$4,560. A simultaneous decline in UoM inflation expectations from 4.0% and a weak consumer sentiment print would extend the rally further.
Bull trigger sequence: Base holds Monday → ECB dovish Thursday → CPI soft Friday → Gold breaks $4,499 → Weekly close toward $4,521–$4,560
Bear Case — Downside Risk: $4,288
The bear scenario activates if the inflation narrative pivots hawkish into Friday. The sequence begins with Tuesday data that surprises to the upside — an NFIB reading above 100.0 or Consumer Credit beat — suggesting US economic resilience that limits the Fed’s urgency to cut. Wednesday’s 10-year bond auction, if it tails (yields clear above 4.68%), would signal that bond markets are demanding more term premium, pushing real yields higher and pressuring gold’s $4,440 resistance into a ceiling that fails to break. On Thursday, a hawkish ECB hold — where Lagarde’s press conference emphasizes lingering inflation risks over growth concerns — combined with a hot PPI print (headline at 0.5%+ or Core at 0.4%+) would strengthen the dollar, break gold below $4,400, and position it vulnerably ahead of Friday. The decisive bear catalyst arrives with Friday’s CPI: a Core m/m at 0.3% or above, or a headline monthly above 0.4%, would force markets to reprice Fed rate cut expectations later into 2027, driving dollar strength and real yield increases that push gold back to the $4,350 structural support. Failure to hold $4,350 on a closing basis would then expose $4,288 — the prior August capitulation low — as the week’s terminal target, invalidating the recovery thesis and opening a deeper corrective phase.
Bear trigger sequence: Hot PPI Thursday → ECB hawkish hold → Hot CPI Friday → Dollar strength → Gold breaks $4,350 → Test of $4,288
This Week’s Daily Analysis
- Monday, September 7 — US and Canadian markets closed for Labor Day and Civic Holiday respectively, compressing gold into a thin-liquidity session; European data including German Industrial Production and Sentix Investor Confidence set the tone for the ECB run-up; the $4,350 structural floor holds the session’s attention.
- Tuesday, September 8 — Chinese Trade Balance data and the NFIB Small Business Index provide the week’s first directional read on US economic momentum; RBA Assistant Governor Hunter and Deputy Governor Hauser speaking in Australia provide Australian dollar context; gold’s positioning ahead of Wednesday’s bond auction comes into focus.
- Wednesday, September 9 — Chinese CPI and PPI offer the global inflation pulse; ADP employment data gives the week’s first US labor market signal; the 10-year US bond auction at 8:01pm UTC becomes the session’s critical market-structure event; Bundesbank’s Nagel speaking in the evening may pre-signal ECB positioning.
- Thursday, September 10 — The ECB rate decision at 3:15pm UTC and Lagarde’s press conference at 3:45pm UTC dominate; simultaneous US PPI and Unemployment Claims create a volatile cross-current; the 30-year bond auction in the evening completes the week’s Treasury supply picture ahead of Friday’s CPI.
- Friday, September 11 — US CPI at 3:30pm UTC delivers the week’s verdict; UK GDP data in the morning provides early session momentum; UoM Consumer Sentiment and Inflation Expectations at 5:00pm UTC extend the inflation narrative through the close; the Fed’s Monetary Policy Report, if released, anchors the medium-term rate outlook.
Analysis based on the XAU/USD 4-hour chart as of September 6, 2026 at 22:55 UTC+3. This article is for informational and educational purposes only and does not constitute financial advice.